Key takeaways:
- As companies stay private for longer, crossover funds exist to capture the value created in that widening window.
- Crossover funds typically hold public equities and late-stage private stakes side by side, with the liquid sleeve funding potential redemptions.
- Dispersion between top-decile and median crossover funds is wide. What defines a winner is access to leading companies with strongest growth potential.
Public and private markets used to sit on opposite sides of a clear line, with capital staying on one side or the other. Vehicles were built around that separation.
Crossover funds are a direct response to that wall eroding: as companies stay private for longer and capture more of their value creation before listing, a growing set of managers have built structures that can follow the capital across both sides of the line, in a single vehicle.
Best of both worlds?
Coatue, Altimeter and D.E. Shaw are all part of a growing list of fund managers that run some version of a dual-book mandate. Coatue’s strategy, for example, is to invest in listed AI and technology companies alongside late-stage private businesses, while retaining the ability to sell stakes and hold cash which is an option traditional long-only or drawdown vehicles typically don't possess.¹
These managers are capitalizing on a long-running trend: companies are staying private for far longer than they used to. The median age of a company at the time of its IPO was roughly five to eight years through the 1980s and '90s, according to research compiled by University of Florida finance professor Jay Ritter. By 2024, that figure had risen to 14 years.²
That gap is where crossover funds operate, and this year, a few yet massive deals dominated the activity. US crossover pre-IPO deal value hit a record $220.9 billion in Q1, more than four times the prior peak of $50.3 billion set in Q4 2021 — but on just 178 deals, versus 425 in that same 2021 quarter, according to Pitchbook. February's mega-rounds drove the spike as firms backed massive pre-IPO raises into OpenAI and Anthropic.³
Inside a crossover fund
Functionally, a crossover fund is a single vehicle authorized to hold both public equities and late-stage private positions. This is possible through specific wrappers (interval funds, evergreen structures, or '40 Act vehicles in the US) that offer periodic, often quarterly, liquidity instead of daily redemption (a characteristic of public markets) or a fixed multi-year lockup (common in closed-ended private markets funds).
In practice, the fund commits to repurchase a set slice of outstanding shares each quarter, commonly 5% of net asset value. To fund these repurchases, the manager sizes the liquid, public-market sleeve to absorb expected redemption volume.
If redemption requests exceed the quarter's repurchase offer, the fund prorates or potentially gates the excess, pushing the remainder to the next quarter. A gate is a contractual feature that triggers whenever redemption demand outruns the pre-set repurchase amount. It's meant to protect the fund's remaining investors from forced asset sales.
How do crossover funds differ
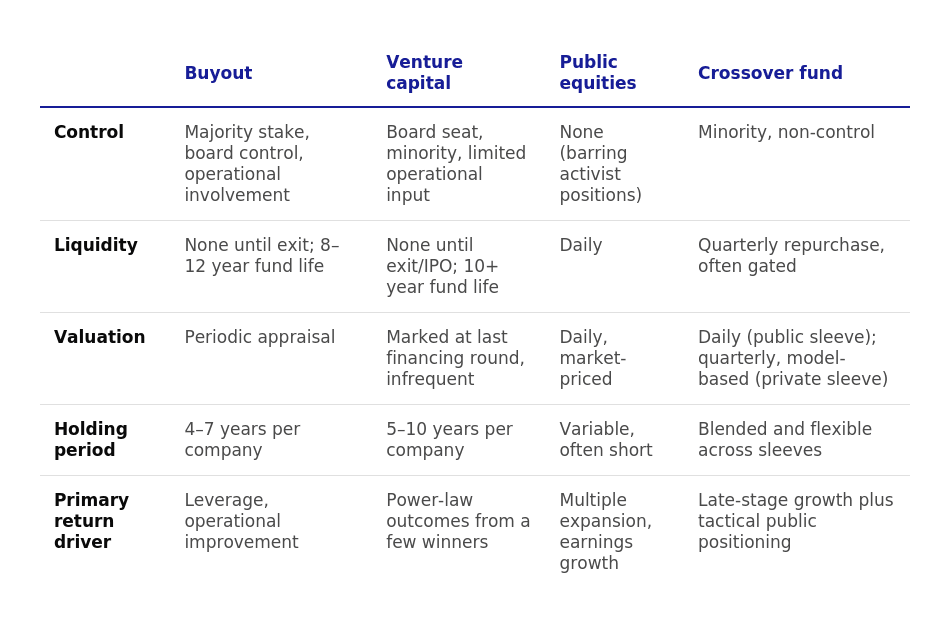
Crossover funds, buyout funds, venture funds and public equities can each play a role in a portfolio, but they operate on different terms. Here's how they compare.
Control. Buyout sponsors typically take board seats, install management and drive returns through operational change. Crossover managers generally take minority, non-control positions and behave more like public-market investors extending into private rounds: buying growth rather than engineering it.
Liquidity terms. Crossover funds sit between the private-public poles. A mutual fund offers daily NAV redemption with essentially no notice; a buyout fund locks capital for eight to twelve years with no redemption right. In contracts, crossover funds operate on a quarterly repurchase cycle, paired with a soft lock which discourages LPs from treating the vehicle as a trading position rather than a longer-term allocation.
Fee structure. Buyout and venture funds typically charge a 2%-and-20% structure, with the management fee levied on committed capital regardless of how much is actually deployed (at the end of the investment period, the base for fees typically shifts to net invested capital). Crossover funds tend to charge a headline fee levied on NAV rather than commitments, since capital is invested from day one and not called down over several years. Most also charge a performance fee following a high water mark, also accrued against NAV rather than paid out of realised gains.
Return drivers. Buyout returns lean on leverage and operational improvement; venture returns lean on a small number of outsized winners covering many losses. Crossover funds blend late-stage private growth exposure with tactical public positioning, which means the fund's returns are exposed to both books.
What makes a crossover winner
For many LPs without the scale or relationships to build a standalone late-stage private book, a crossover fund is a reasonable way to get that exposure through a single allocation.
That said, manager selection matters immensely. Dispersion across crossover deals is wide, according to Neuberger Berman's analysis of PitchBook data: over the past two decades, investments in the top-decile made by crossover funds have delivered gross IRRs 40% to 160% higher than the median deal.⁴ A gap that size means picking the right manager can matter as much as the decision to allocate to the asset class at all.
The clearest differentiator in a manager is a proven, repeatable underwriting process. Successful crossover investors tend to have a strong record of identifying companies on a “dependable glide path” to an IPO — businesses with the revenue quality, governance and strong balance-sheets.